The Accounts Chamber called for an increase in the tax on excess income for gold
The Accounts Chamber has commented on the government bill on the tax on super-income of subsoil users. Special criticism received a reduced tax rate for gold mining companies
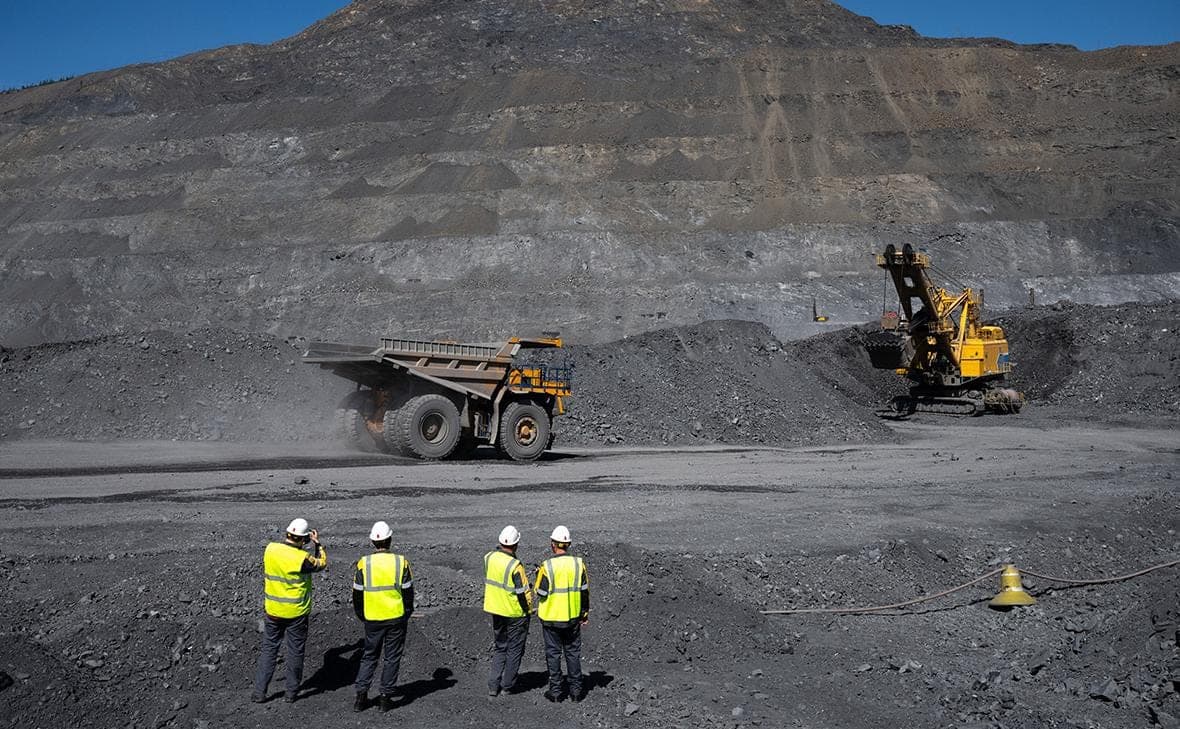
The Accounts Chamber considers it necessary in the new budget cycle to increase the tax burden on gold mining companies and move from one-time fees to systemic taxation of mountain rent. The control body explains this by the growth of world gold prices and the high profitability of the industry, indicated in its conclusion on the draft federal budget for 2027-2029.
Analysis of financial indicators of subsoil users revealed a significant potential for additional revenues of the mineral extraction tax (MET) in the extraction of precious and non-ferrous metals, complex ores and raw materials for the production of mineral fertilizers. The current level of taxation of these resources is considered insufficient.
The joint venture notes that in 2020-2025, the legislation was repeatedly changed to withdraw super profits from the extraction of solid minerals. Among the measures taken are the increase in MET, the linking of tax rates to world prices for raw materials and the introduction of a one-time tax on superprofits in 2023. Instead of expanding the practice of one-time fees, the Accounts Chamber proposes to develop systemic measures to improve taxation of the extraction of certain types of minerals.
Separately, the conclusion indicates the need to establish an increased tax rate for gold mining. The government’s Super Income Tax (SIT) bill provides for a 20% rate for gold versus 30% for most other minerals.
The average world price of gold in 2025 amounted to $3,442 per troy ounce, an increase of 91% compared to 2021, the JV concluded. According to the forecast of socio-economic development, the price of gold in 2026 will be 25% higher than the level of 2025, in 2027 - by 38%, in 2028 - by 41%, in 2029 - by 44%. The audit chamber also notes that the average industry profitability of costs in gold production significantly exceeds the indicators of other mining industries.
How the NSD works
The Ministry of Finance submitted to the government a budget package for 2027-2029, including a bill on the tax on super-incomes for subsoil users. The tax is proposed to be levied in 2027-2029 from companies producing iron ore, non-ferrous metal ores, precious metals, raw materials for the production of aluminum and fertilizers and a number of other solid minerals. With the production of oil, gas, coal, diamonds, uranium NSD is not charged. The rate will be 30% for most minerals and 20% for gold.
The object of taxation will be the additional cost of extracted raw materials, arising when the average world price for it exceeds the base weighted average price of 2025. To create a tax base, the growth of the average price of raw materials in 2026 should be at least 10%. The base price for subsequent periods will be indexed: for the calculation of tax for 2027 - by 10%, for 2028 - by 21% compared to the figure of 2025. The bill also limits the amount paid to NSD to the amount calculated on the basis of the indicator “15% of estimated revenue minus the mineral extraction tax (MET)”.
According to the Finance Ministry, the tax should bring the budget 683 billion rubles. for three years. According to RSPP estimates, with the same macroeconomic prerequisites, total revenues from NSD can amount to about 1.1 trillion rubles, that is, about 1.6 times more than the estimate of the Ministry of Finance.
What analysts say
Analysts interviewed by RBC believe the transition to a more predictable taxation of mining rent is justified, but they differ in their assessments of the need to increase the burden on gold mining. Among the possible solutions, they call a change in MET rates depending on world gold prices and the introduction of a more flexible taxation scale. At the same time, experts warn that higher taxes can reduce the attractiveness of developing fields with high costs.
Sergey Krivohizhin, an analyst at Sinara Investment Bank, believes that the development of separate taxation rules for different segments of the mining and metallurgical complex would make the load more predictable and understandable for producers. This would allow companies to consider future payments as they plan their budgets. However, this requires detailed elaboration of the mechanism by business and authorities, and so far the initiative looks more like a “theoretical appeal”, the analyst notes.
Portfolio manager of Alfa-Capital Dmitry Skryabin also believes that the transition to “long-term rules of the game” is justified, which, unlike one-time withdrawals, look rational both for the budget and for sector companies and investors.
Finam analyst Egor Vershinin draws attention to the fact that the draft law on NSD does not solve the problem of systemic taxation of mountain rent, and its main problem is the instability of revenues, since even a small change in prices can affect fees. A more predictable alternative to a temporary tax would be the development of permanent mechanisms based on MET, including already existing mechanisms linking the tax burden with world prices for raw materials, Vershinin believes.
Dmitry Orekhov, Managing Director of the rating agency of the NKR, emphasizes that the improvement of MET should take into account not only the growth of raw material prices, but also the dynamics of costs, the quality of the resource base, production conditions and the capital intensity of projects, so that the withdrawal of superprofits does not reduce the ability of companies to finance geological exploration and production development.
Gold rent
Commenting on the proposal of the joint venture to establish an increased rate of NSD for gold mining, Krivohizhin proposed to consider an additional price threshold for MET. Now, with the price of gold above $ 1,900 per ounce, the MET rate rises to 10%. “Perhaps under the “increased rate” refers to the introduction of another cut-off – say, $3,000 per ounce, above which the MET rate will be increased,” the analyst says. As a possible benchmark, he cites a rate of 20-30%, stressing that a particular level requires a separate estimate.
At the same time, Krivohizhin warns against mechanically increasing the tax burden. According to him, the higher profitability of gold mining compared to other mining industries does not fully take into account the peculiarities of investments in the industry: the costs of exploration and development of deposits are higher here, and the terms of working out assets are lower. In addition, the increase in prices allows to involve in the development of the field with higher costs, increasing the growth of investment in the sector. Raising taxes can make such projects less attractive or unprofitable.
According to Scriabin, the average cost of gold mining in the industry is about $2,000 per ounce. At a metal price above $4,000 per ounce, the return on free cash flow of gold mining companies can exceed 50%. Therefore, according to the analyst, the logic of the state to withdraw part of the excess profits caused by favorable price conditions is clear. At the same time, the amount of additional tax and the indexation of the base price from which the tax burden is calculated should be discussed separately.
Vershinin also believes the arguments of the Accounts Chamber in favor of a higher tax burden on gold mining are justified. However, he opposes a single higher rate for the entire industry: the potential for super-profits of large low-cost producers is significantly higher than that of companies developing deposits with poor ores.
The bill sets a 20% rate for gold versus 30% for other companies, probably considering the already existing allowance for MET. However, the key problem is not so much in the size of the rate as in the design of the tax, Vershinin says. According to Finam calculations, at the current price of gold ($4196 per ounce), the Polyus tax for 2028 does not occur: the excess over the indexed base is 9.2% with a threshold of 10%. Therefore, in this scenario, raising the rate from 20 to 30% does not change anything. At the price of gold from $ 4400 per ounce, aggregate payments for 3 years can amount to 89-96 billion rubles. against 55.6 billion rubles. at the current price. At a long-term price of $4,000, the tax in the Finama model occurs only for 2026, the analyst notes.
As an alternative, the analyst proposes to introduce a smooth scale of taxation depending on the price of gold or include the rent component directly in the MET.
Earlier, the RSPP sent the Ministry of Finance proposals for the revision of the NSD (about these proposals RBC told in detail on October 2). The Union, in particular, proposed not to levy tax on unprofitable enterprises, to take into account industry specifics and allow to include paid NSD in expenses when calculating income tax. As an alternative, the RSPP also proposed a temporary increase in the income tax rate by 0.5-1 percentage points for a period of three years.
Representatives of the gold mining industry interviewed by RBC have already warned that NSD can reduce the profitability of enterprises and do not take into account differences in the economy of individual projects. They pointed to high capital costs and a long investment cycle in the industry, advocated tax exemption for unprofitable companies and a more selective approach to determining the tax burden.
RBC sent a request to the largest gold mining companies.