The global crisis of diesel fuel: the signs and risks
The global diesel market has fallen into a full-blown crisis
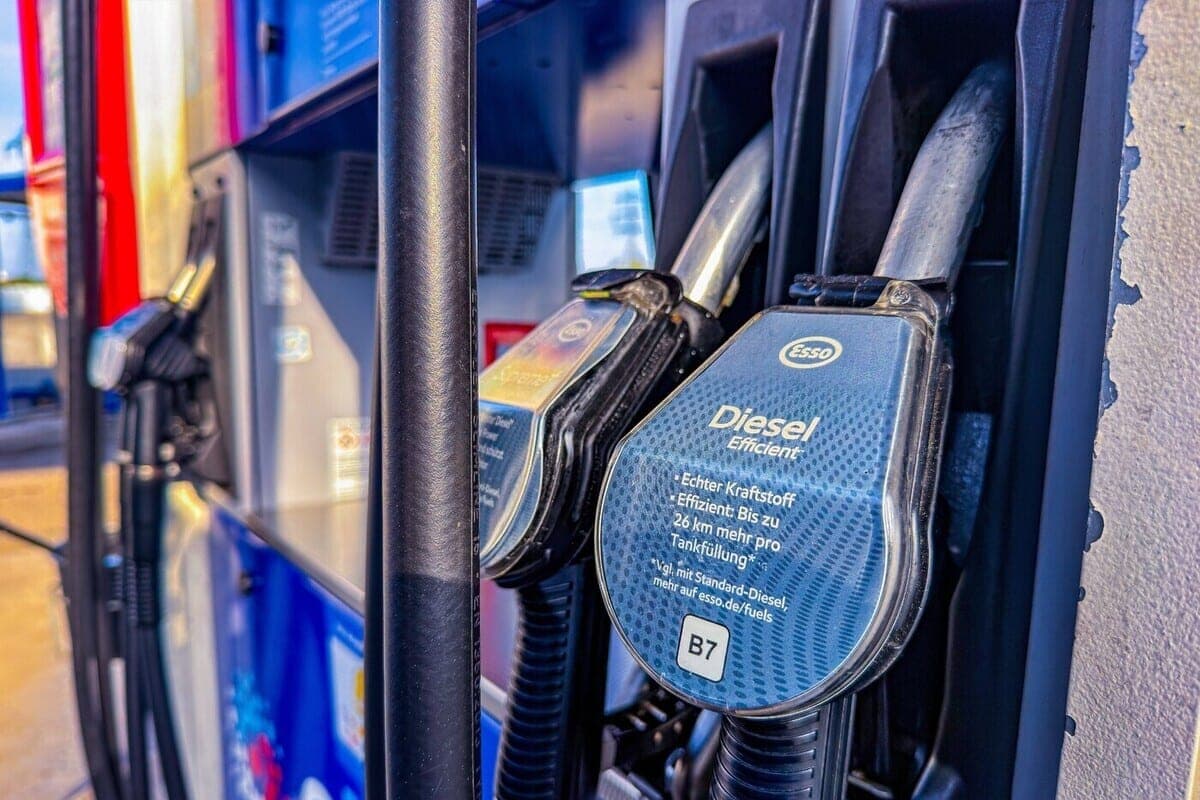
The problem is that due to prolonged supply disruptions, diesel stocks are reduced at atypical times: usually before the winter heating season (in September-October), they grow. Accordingly, world consumption is also declining, which in turn leads to a slowdown in industry and overall economic growth. Yes, the situation does not mean that fuel disappears at all gas stations everywhere. The average retail price in the EU countries reached €2.27 per liter, which is 39% higher than in February 2026; in the UK, the figure was 41% higher, in the US – 64%. And these are the prices at gas stations, and not purely wholesale quotes.
But the so-called diesel margin – the difference between the price of final fuel and crude oil – has risen particularly sharply. In Europe in early September, it was close to $ 100 per barrel, but in the first half of October it fell to about $ 57. That is, in any case, diesel remains very expensive due to the high cost of oil (currently $114 per barrel of Brent) and transportation, as well as limited supply. According to the IEA, import-dependent countries of the EU, Africa and Latin America suffer the most. The EU consumes a lot of diesel in freight transport, agriculture and industry, while it is facing a decline in supplies from the Middle East. African states lack the currency to pay for imports, with rising diesel prices quickly translated into rising prices for food, water, generating electricity and public transport. In Latin America, the most vulnerable countries are those that do not have enough of their own refineries, primarily Paraguay and Uruguay.
According to the president of the Association of Exporters and Importers, Arthur Leer, the reasons for what is happening go far beyond geopolitical events in the Middle East, although this conflict was the key trigger that triggered the crisis mechanisms. A combination of systemic factors affected: reduction in oil refining volumes, disruption of existing supplies, lack of necessary spare refining capacities and gradual exhaustion of previously formed energy reserves in the off-season.
Buyers willing to overpay
“I believe that there are already reasons to talk about the crisis,” says Vladimir Chernov, an analyst at Freedom Global. It manifests itself in the reduction of available supply, depletion of stocks and high cost of urgent supplies. The global shortage does not mean that diesel runs out at all gas stations at the same time. Consumers continue to receive fuel, but these supplies are supported by accumulated reserves and higher prices. According to the October report of the IEA, world exports of diesel and gas oil in September were almost 700,000 barrels per day lower than in the same month last year. Wholesale prices in September exceeded $200 per barrel in Singapore and reached $220 in Europe and the United States. The Agency also records an increase in premiums for the nearest deliveries relative to future ones. This is a sign that buyers are willing to overpay for the fuel that is available now.”.
American statistics confirm the tension in the global diesel market. According to the U.S. Energy Information Administration (EIA), in September, East Coast distillate stocks were 32% below the seasonal average for 2021-2025. The average retail price of diesel in the US for September was $6.29 per gallon. Another indicator of the seriousness of the situation is the emergency actions of states. In a statement on October 15, the IEA said it was accelerating supplies from reserves, including more than 20 million barrels of diesel. When emergency stocks have to be expended expeditiously to ensure the market, we are talking about problems of physical supply, and not only about fluctuations in stock prices. As Chernov notes, diesel is especially important for the economy, since cargo transportation, agricultural machinery, construction and extraction of raw materials depend on it. The carrier cannot quickly replace the fleet of trucks, and the farmer refuses to harvest until prices drop. Therefore, initially the business takes the increased costs on itself, then tries to pass them on to customers. Accordingly, the main risk lies in the spread of high prices throughout the chain of production and delivery of goods.
The world is “eating” strategic reserves
“We do not see such a severe deficit in other segments of the energy market — neither gasoline nor jet fuel comparable problems, — says the expert of the Financial University under the Government of the Russian Federation Igor Yushkov. Saudi Arabia, the world’s third-largest exporter of diesel fuel after the United States and Russia (at the end of 2025), does not ship any significant volumes today due to the closure of the Strait of Hormuz. Our country stopped exports in August due to a series of drone strikes on oil refining facilities. Moreover, in the case of crude oil supplies, the situation is different: it is to a certain extent softened by bypass pipelines – the East-West pipeline in Saudi Arabia with a length of 1,200 kilometers or the oil pipeline in the UAE, which connects the Khabshan offshore field in Abu Dhabi with the port of Fujairah on the Gulf of Oman. So there are options.”.
According to Yushkov, the world quickly used up commercial reserves of finished oil products and now “eats” strategic, which, of course, are not infinite. And the higher the degree of exhaustion (largely due to the withdrawal from the market of Saudi and Russian diesel), the higher the prices and the more acute the general crisis. India, the fourth-largest global exporter, is also contributing to the deficit. Having created a once powerful specialized infrastructure, built dozens of refineries on the coast, today, due to the Middle East events (as well as pressure from Washington, deliberately forcing India to abandon purchases of Russian crude oil), this country is deprived of the ability to supply diesel fuel abroad in former volumes and as regularly as before.
As for Russia, it still produces more diesel than it consumes. In the past, not burdened by raids on refineries, we exported at least 50% of volumes, since the domestic market more than enough of the rest, the analyst notes. The current production infrastructure dates back to the Soviet era, when the focus of the economy on diesel fuel was much more global and obvious, and when few had personal cars on a gasoline engine. Diesel massively went to the needs of the army, agriculture, utilities, public transport, mining industry (career equipment), reminds Yushkov. Russia has inherited, preserved and modernized its plants and consolidated this historical bias towards the production and consumption of diesel fuel. It is likely that in the coming months it will return to export after a forced pause, in any case, the ban on it is valid until the end of October, and significant surpluses have formed in fuel storage by this time.
Deal factor
Meanwhile, according to Reuters, the first tanker with 40 thousand tons of Russian diesel fuel (low sulfur content) went to New York. The Maltese-flagged Agioi Fanendes ship loaded this shipment at the port of Primorsk on the Baltic Sea. It is expected to arrive in the United States on November 7. The event is certainly a breakthrough, since on April 1, 2022, Washington (the administration of President Biden) imposed a ban on the import of Russian oil products. And within the framework of the agreement of October 9, 2026 between Presidents Vladimir Putin and Donald Trump, the United States actually canceled it for six months, until April 7, 2027. Russia has pledged to deliver more than 300,000 tons of diesel to America “immediately,” another 500,000 tons in November, and about 1 million tons immediately thereafter. In addition, about 3 million tons of fuel were discussed, if the state of the Russian refineries allows to provide such a volume. According to a recent statement by Deputy Prime Minister Alexander Novak, three tankers with diesel fuel are already moving towards America, and by the end of the year Russia will export about 3.5 million tons per month.
Will the U.S.-Russia diesel deal reduce the global deficit? Yes, but at first to a very small extent. The initial batch of 300 thousand tons is 2.25 million barrels (1 ton = 7.45 barrels), and the American economy, according to the IEA, consumes about 3.8-3.8 million barrels per day, or about 520 thousand tons. This is approximately 13-14 hours of continuous consumption by one country. But it’s not just about numbers. There are also moments of political and psychological nature that matter not so much for the entire world market, but for two actors – Washington and Moscow.
“Now Trump is vitally interested in Russia as soon as possible began to saturate the world market of diesel, because one way or another it should affect stock prices,” says Igor Yushkov. The midterm elections to Congress are on the nose, there are only a few days until the date of November 3, and the average cost of diesel fuel in the United States for the week increased from $6.23 to $6.51 per gallon. Which, of course, does not please the electorate. For the Kremlin, the deal with the White House is beneficial both politically and economically: in addition to additional budget revenues, we received a precedent for easing extremely tough sanctions imposed in the spring of 2022 on Russian oil, oil products, coal and gas.
According to Yushkov, the final volume of supplies will depend on the state of the refinery: if in the next month or two it is possible to remove the main damaged capacity from repairs and if repeated strikes on the plants can be avoided (or prevented), then Russia will enter full-scale production of diesel and to some extent restore exports.
Diesel arithmetic
“The scale of the effect depends on how much additional fuel actually enters the world market,” says Vladimir Chernov. If the Russian diesel simply replaces the buyer, the total supply will not increase. The benefit in this case will mainly be associated with changes in routes, settlement conditions and delivery costs. If you conditionally distribute a million tons per month, then when recalculating 7.5 barrels per ton it is about 250 thousand barrels per day. According to my calculations, this volume corresponds to a third of the September decline in global exports of diesel and gas oil, which was reported by the IEA. This is a notable value, but the comparison makes sense only if the entire volume is additional. This is where the main uncertainty lies at the moment. According to S&P Global, the announced deliveries may partially match existing export flows. Therefore, it is not possible to automatically add the entire declared volume to the world supply. For a stronger effect, it is necessary to increase output at Russian refineries and exports in excess of what is already received by foreign buyers.”.
There is also a separate issue of direct import into the United States. S&P Global points to legal objections related to a congressional ban on imports of Russian energy. Therefore, according to Chernov, the presence of the OFAC license (US Treasury) does not allow to consider all legal issues of direct American purchases finally closed. Therefore, at the first stage, the positive effect of the transaction will be very moderate. A more significant reduction in world prices is possible if permits are followed by the restoration of oil refining in Russia, regular additional shipments and replenishment of reserves. And even if there is a supply surplus in the market at some point, it will not mean the end of the crisis.
It is not enough to meet the current needs of consumers, it is also necessary to form a surplus to fill storage facilities, Chernov notes. While reserves are scarce, any accident, delivery delay or unexpected cooling will cause sharp price spikes and destabilize the situation. According to the IEA, although the diesel market may move to a small surplus in the first quarter of 2027, the accumulated inventory deficit will not be fully compensated until the second half of the year.
In the meantime, we summarize, products and delivery services will rise in price; construction materials and goods with long logistics; bus transportation. Heating outages (diesel boilers in private homes) and electricity (diesel generators) in remote settlements will become more frequent. An ordinary person is waiting for gloomy surprises, including food with a short shelf life - vegetables, meat, milk and frozen products, the transportation of which is largely provided by diesel trucks, trucks and refrigerators. Certain drugs fall into the same category. The list goes on and the risks remain very real.